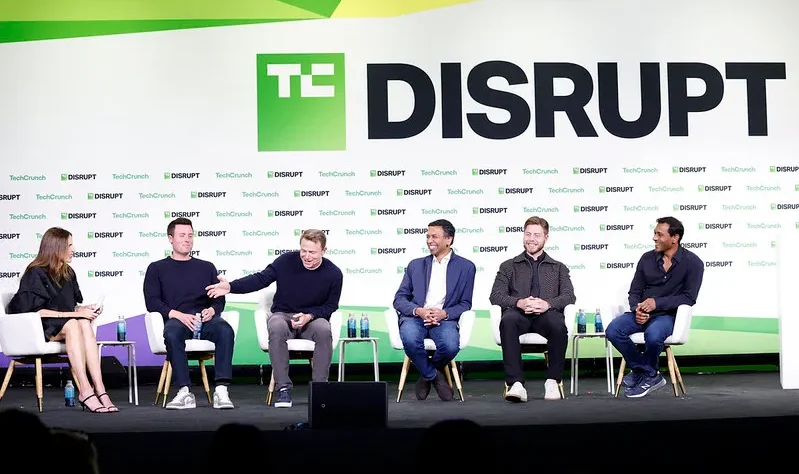
The team occasionally shifts. Three years ago, I interviewed four partners from Benchmark, and currently, three of them have departed from the firm. The financial commitments have altered as well. This summer, Benchmark revealed $2 billion across two funds, marking only the second time in its 31-year journey that it has deviated from its usual practice of raising much smaller funds.
However, at this week’s TechCrunch Disrupt, the five partners of the venture firm effectively presented themselves as a cohesive group that isn’t rushing, unlike many of their competitors. While the world seems to be picking up speed, they are investing at the traditional pace Benchmark has maintained: just two or three new investments per year for each partner. Despite the overload of information globally, their Monday meetings among partners lack a formal agenda. And though economic signals suggest challenges ahead, they appear unfazed, interpreting many warning signs as results of X-fueled frenzy.
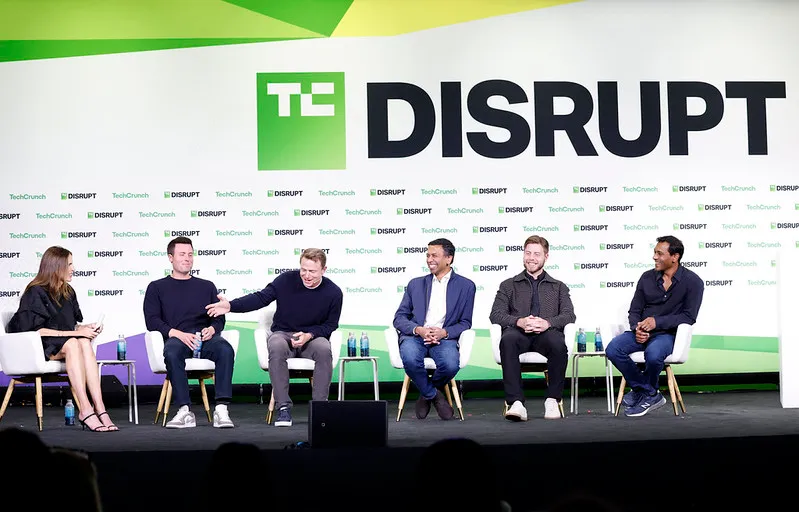
Here’s what the five general partners of Benchmark—convened on our stage—shared at the event. Some comments have been abridged for clarity; the full interview can be viewed at the conclusion of the article.
Benchmark has progressed in several ways, such as having a larger core fund and a new growth fund. How do you navigate change without compromising what defines Benchmark?
Peter Fenton: The foundation that remains unchanged is the core fund: collaborating intimately with founders right from the start. This typically involves a 10-to-15-year commitment, [working] closely, which doesn’t scale. There’s been inflation as well. We maintained the core fund at $500 million for two decades, and it has now been adjusted to align with the current economy, which we hadn’t previously done, and that was likely a miscalculation on our part.
[Regarding the growth fund] it represents an expansion of our mission. In some aspects, we’re authorized by our ecosystem to move beyond just our core early-stage activities. [Not having this previously] was a limitation for us. A range of opportunities presented to Benchmark could have yielded returns between 10 and 1,000x for us, but we were limited by our early-stage restrictions.
Are you considering making a few bets with that $1.25 billion growth fund?
Fenton: We all have varying perspectives, which is the advantage of a partnership. I’d personally love for us to experience, as that famous J.P. Morgan paper suggests, the agony and ecstasy of a concentrated portfolio. If the fund excels, one or two investments will account for 90% of the returns. So, I think it’ll be around four to six, maybe seven to eight.
Ev, you joined Benchmark late last year. You’ve been with Founders Fund, Bond, and Kleiner Perkins. How does Benchmark stand out?
Ev Randall: Every firm fundamentally reflects the individuals within it and their collaborative dynamics. Some operate with a highly hierarchical structure, containing a 50- or 60-member investment team with tiered processes, while others are small partnerships. Early in my career, I was attracted to small partnerships for their capacity for greater throughput and clarity in discussions, allowing for decision-making without convoluted corporate hierarchies. It’s akin to being part of a sports team.
Moreover, it’s essential to connect with your people. You must find those you not only like but also respect. At Benchmark, with the current group of GPs, it was apparent that everyone got along, but there was much more to it—it’s a team that respects and educates one another. This combination of qualities is rare, and once I recognized it, I was eager to join, and I believe Jack felt similarly as a newcomer.
Jack, you came on board in February, but just a year ago, you raised a second, $275 million fund for your own firm in what you described to the Wall Street Journal as a week. You host a highly popular podcast. What motivated you to join Benchmark?
Jack Altman: It’s amusing. I recorded a podcast with these guys earlier this year, during which we discussed the commitment to remaining a small fund. More than that, I perceived their desire to be the first call for founders, to maintain focus, and to genuinely care. Much of this industry is entangled in finances and reputations, yet what struck me about the Benchmark team, then and even more so as I got to know them, was their authentic concern for founders and helping companies. While I appreciated being an individual investor, in such a chaotic market, I found it challenging navigating alone. Having a group of smart, dedicated individuals to learn alongside has been fantastic. There’s truly no better place for growth.
I hear you gather on Mondays without a set agenda.
Chethan Puttagunta: Jack attempted to create an agenda. [Laughs.]
Altman: I’ve got an agenda ready for next Monday.
Eric Vishria: It’s quite arbitrary, actually. It serves as an ongoing dialogue. Amidst rapid change, we explore what’s becoming achievable that wasn’t possible half a year ago, and who’s shifting dynamics. We discuss companies we’re meeting, what has captured our interest and why, plus insights from board meetings. While trying to systematize it is tempting, the beauty of our group of five lies in the fact that we don’t have to. It’s a prolonged conversation only viable if we’re small and genuinely enjoy each other’s company. Following this session, we’re having dinner with one of the few entrepreneurs who has built a multi-hundred-billion-dollar enterprise, someone we’re not invested in—just to broaden our perspectives.
Puttagunta: Not having an agenda allows room to be responsive. If a founder needs assistance securing an executive or forming a strategic partnership, the five of us can step in to help.
You operate as an equal partnership. Can one person veto a deal?
Puttagunta: It’s unclear. We don’t have established rules regarding that.
Altman: I honestly don’t know. I was waiting for someone else to say something.
That’s never occurred?
Altman: Due to the firm’s design around few deals, having rigid protocols isn’t actually desirable. If we invested in 100 or 200 firms annually, you’d want a CRM and an official voting approach. Since that’s infrequent, the minimal structure is a significant advantage.
Fenton: One of our brand’s unique features is that we don’t rush to judge winners or losers. It’s not Shark Tank. We feel a sense of wonder, for lack of a better term, at all the potential . . . The rare occasion when someone does come in that’s polarizing — the entrepreneurs notice that. If one member of the group doesn’t resonate with you, we may not be the best partner.
Businesses are experiencing growth at unprecedented rates. It seems easier to feel like you’re missing out on prospects if you’re not investing more frequently. Have you increased your speed?
Puttagunta: I believe our pace remains steady. A core truth of venture capital in our field is that we won’t be involved with every thriving business, and that’s perfectly fine. There are companies we recognize, where we see the entrepreneur has specific strengths, and we aspire to enhance that strength. Our role is to discover how to collaborate with that entrepreneur. It doesn’t matter how much funding they aim to raise, what structure, or their current status. You simply must navigate through everything.
One trend that founders are keen on is VCs backing rival firms. Has the VC-founder relationship shifted due to rapid business expansion and encroachment into each other’s markets?
Vishria: We believe strongly in committing to an entrepreneur, and with that commitment, we affirm that we will engage closely with them in whatever endeavor they pursue, which should matter to them just as it matters to us. The harsh reality today is that every company is progressing rapidly, leading to natural shifts in business focus, pivots, or transformations, which will result in conflicts. That’s simply part of the current landscape. . .
Naturally, we maintain confidentiality and take necessary precautions, and we have been fortunate to avoid direct confrontations [as seen recently between rival companies Factory and Cognition]. . . that commitment to exclusivity in specific domains is truly vital. But circumstances are changing. There’s no doubt about it.
Puttagunta: Additionally, individuals are exceptionally ambitious in this AI age. With the costs of developing new products dropping significantly, founders recognize new opportunities and are eager to exploit them, suggesting that overlaps between competitors will likely increase. Nonetheless, it’s possible to maintain healthy relationships and mutual respect.
Jack, have you made any investments for Benchmark yet, and if yes, did you feel a lot of pressure with that initial deal?
Altman: I have made several, some of which are fairly recent and not all are public yet. My background is in software, but since joining, I have also ventured into chips, robotics, and infrastructure. When I joined, someone asked how my onboarding was, to which I responded, ‘It was perfect. There was no onboarding.’ Either Chethan or Eric mentioned early on, ‘Hey, you might feel pressured with your first deal. Don’t. You’ll be making numerous investments while you’re here. This industry involves unpredictable power dynamics. The chances of your first one being a major success are low.’ . . . I trusted they understood my approach as an individual and as an investor, and I aimed to remain true to that.
The dynamics of these decisions are heavily influenced by the group. The investments I made, I doubt we could have secured without the support of my partners. I’m not sure I would have known how to say yes without them.
Eric, investing in the AI chip company Cerebras was an unusual choice for Benchmark when it occurred. What led you to proceed with it?
Vishria: We invested in the spring of 2016 in their inaugural round. We hadn’t engaged in hardware investments in a decade. The founders appeared capable, their thesis was straightforward, and I struggled to grasp most of the rest. The Sunday night prior to their pitch to the partners, Peter shared with me that it contradicted everything he had learned in venture. However, after the Monday pitch, he had changed his mind. A significant part of the decision-making was understanding each other’s instincts. This marked the start of a journey filled with numerous highs and lows and several potential company failures along the way, and it’s far from finished. The passion for connecting with a founder and their vision is why we pursue this work.
Fenton: Andrew and his co-founders are outliers. What they proposed was unconventional, and this is evident today, as people react negatively to the stock due to its polarizing nature. That’s precisely where we need to position ourselves as investors. If everyone agrees, why would there be a startup?
On that subject, Cerebras was priced at $185 when it went public earlier this year, rose to $350, and has now returned near $185. What are your thoughts on this?
Vishria: About six weeks prior to the IPO, I presented multiple stock performance graphs: CoreWeave, Datadog, DoorDash, Amazon. The fluctuations they experience, from peak to trough, are astounding—often moving 500% within a year. So, who can say? You manage what lies within your control, and update the public markets every 12 weeks. Being a publicly traded company requires a steel stomach, and employees need to comprehend that.
Your former colleague, Bill Gurley, has long claimed that the conventional IPO process is flawed, with the IPO ‘pop’ benefiting bankers and their clients rather than the company. He advocates for direct listings. Does anyone share that perspective?
Vishria: I believe I may be the sole one here with direct listing experience. It can absolutely make sense in the right context. However, for this wave of AI firms, it’s unlikely since they require substantial capital. Ultimately, IPOs are about raising funds. Cerebras secured $6 billion. That’s significant, hence I think it’s improbable for this group mostly due to their capital needs.
Could a serious correction be on the horizon? Many AI firms have depleted their free cash flow. Borrowing costs are substantially high. Recently, we also witnessed the first AI bankruptcy with Character AI.
Randall: Predicting macro events with precision is always a challenge. Since I began investing, the most substantial change has been in the information landscape. Character.AI was the remnant of a company whose founder and team were acqui-hired by Google a year and a half ago, and it previously sold for $2.3 billion; its Chapter 11 filing perceived as an AI chill effect illustrates how the data environment for public tech equities is captured in this frenetic X echo chamber.
When you observe the market today and analyze CoreWeave and Nebius alongside others, those values correspond to the ARR figures of two private companies likely to go public within the next year . . . There’s a significant amount of capital expenditure and investment flowing through the anticipated health of OpenAI and Anthropic.
Our firms are inundated with demand and struggle to meet the computational needs of customers willing to pay them with favorable gross margins. There’s nothing fundamentally wrong with the AI ecosystem. What is troubling is the volatility stemming from often misleading or exaggerated data meant to attract clicks. I genuinely believe that OpenAI and Anthropic going public would stabilize the market, preventing shifts of 5% to 10% every time an anonymous account alters an estimate.
Those two companies have also significantly shifted the center of gravity back to San Francisco. Must a founder be situated in San Francisco now? Are you considering companies beyond California?
Altman: I wouldn’t say being in San Francisco is a requisite for founders, but it undeniably is currently the easiest place to secure talent, capital, and clients. Everyone [on the team] engages with firms outside of San Francisco, yet we’re also in San Francisco daily. So, while it’s not mandatory, I’d argue there’s a strong bias given our situation.
Fenton: Historically, over 90% of capital returns have originated from companies established here. There are compelling stories outside of this concentrated trend — Shopify is an exemplary case, as is Ramp — yet the ecosystem that develops when a successful company emerges fosters a backdrop of exceptional executives [and] ambitious individuals, raising the bar for success. I don’t believe this systemic occurrence has transpired elsewhere like it does here.
Randall: I’m reflecting on the non-SF-based firms I’ve encountered in the past 18 months that did not express interest in engaging with San Francisco. They are either opening an office here, spending a significant portion of their time in the city, or planning to relocate to San Francisco. Iron sharpens iron. If you aim to associate with peers that will refine you into your best self, it’s hard to find a locality that accomplishes that better than San Francisco in this current AI era.
[embedded content]
Purchasing through links in our articles may earn us a small commission. This does not influence our editorial independence.