TechCrunch Founder Summit’s schedule disclosed: Access fundraising, recruitment, and AI insights in Boston on November 4

TechCrunch Founder Summit’s schedule disclosed: Access fundraising, recruitment, and AI insights in Boston on November 4

On November 4, the Founder Summit by TechCrunch will host an essential one-day intensive on building startups at Boston’s SoWa Power Station. Founders shouldn’t have to endure the toughest lessons in the toughest ways, and this event aims to simplify the challenges of launching a business and amplify the rewards.

Rather than spending months on trial and error, you can gain direct insights from the investors and founders who have faced the decisions you’re now navigating. We’re covering everything from securing funding and recruiting to AI strategy and dominating your sector.

Don’t just take our word for it. Check out the complete lineup of speakers and sessions we have arranged for the Founder Summit below, and secure your spot for the event. All tickets are offered at the most affordable rates available, making this the ideal moment to take action.

The TechCrunch Founder Summit Official Agenda Unveiled

Without any more delay, here’s the official agenda. Familiarize yourself with every session and speaker listed on the event agenda page.
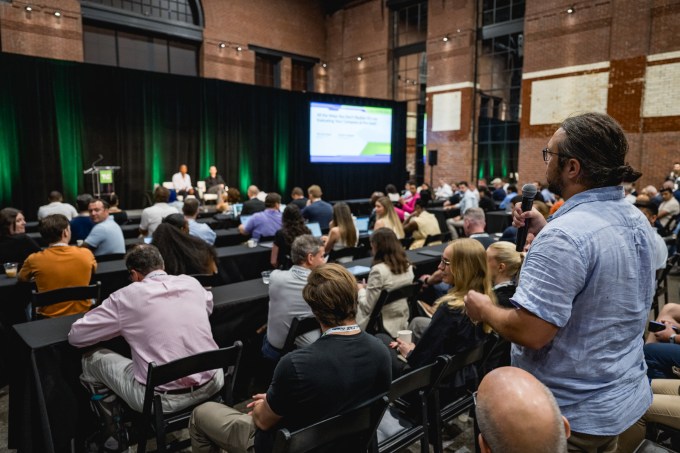
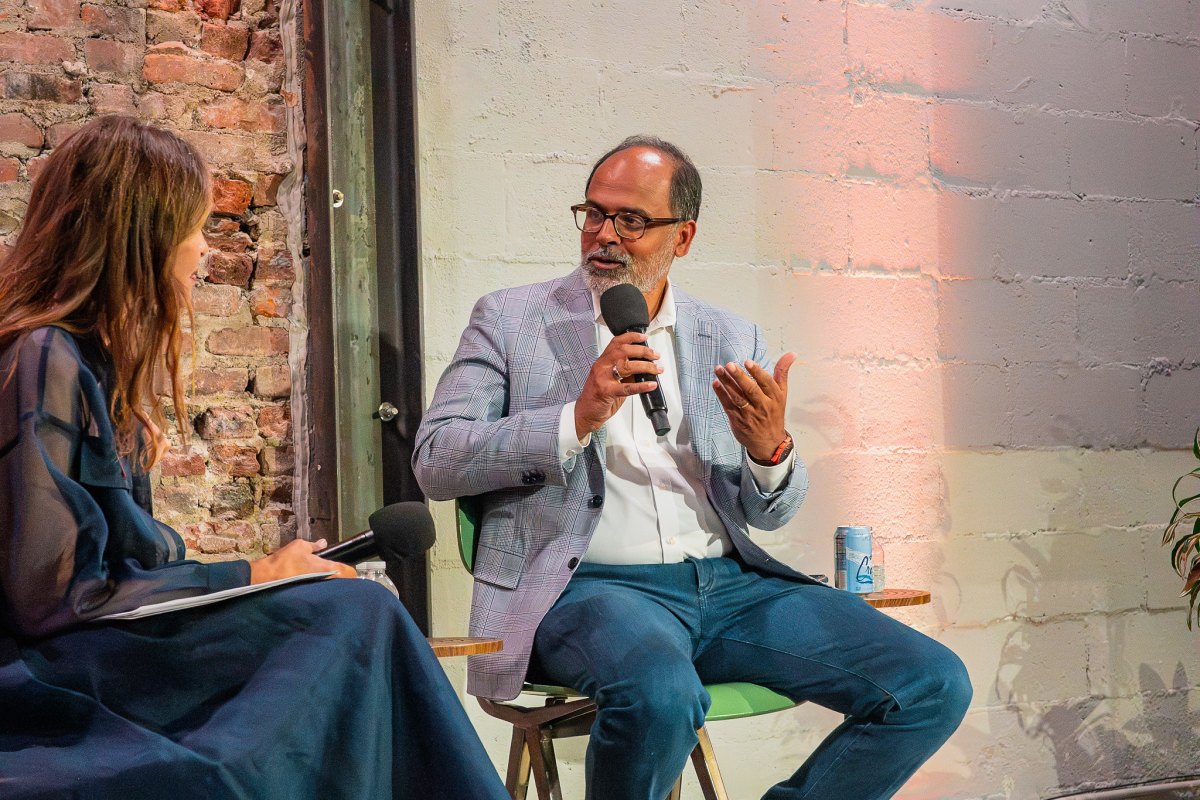
Audience at TechCrunch Founder Summit breakout
Image Credits:Halo Creative

The New Guidelines for Fundraising 

Securing funds has never been simple, yet the strategies continue to evolve. Brian Devaney, partner at Underscore, will clarify what investors currently desire, how founders can distinguish themselves in a saturated market, and the areas where founders frequently lose influence without being aware. Expect a straightforward examination of today’s fundraising landscape, covering everything from initial investments to term agreements, and the blunders that can determine the fate of a funding round.

The CEO Role Is Ever-Challenging 

While the job title remains constant, the responsibilities shift with every phase of a company’s expansion. HubSpot co-founder and Sequoia partner Brian Halligan will discuss the insights he has gained from mentoring and supporting startups through periods of swift growth, difficult choices, and continuous adaptation.  

This session will delve into how founders can transition into effective CEOs, sidestep typical leadership mistakes, and create businesses that will succeed long after their initial launch.

Designed for AI from the Start 

Integrating AI features is one thing; establishing an AI-centric business is an entirely different endeavor. Lior Div, co-founder and CEO of 7AI, will assess what adjustments must be made when AI is integrated as the core of a startup rather than just an addition. This session will explore everything from team organization and product innovation to operations and market entry strategies, examining what founders need to reconsider while operating in the AI age.

Not All Dollars Are Created Equal 

Raising funds is frequently viewed as a key achievement, but selecting the appropriate investors can influence a company’s trajectory long after the funds are received. Following an $11 million funding round for Cogent Security, co-founder and CEO Vineet Edupuganti gained firsthand knowledge of what differentiates valuable partners from costly distractions. This session will discuss how founders should assess investors, manage compromises, and think past valuation when constructing their investment table.

Identifying the ‘King of the Hill’ Company — Hidden Indicators That Define Market Leaders 

Innovation is essential for addressing the world’s greatest challenges, yet only select companies are likely to evolve into market-defining leaders on a large scale. In this session, TDK Ventures investment director Tina Tosukhowong unpacks the firm’s “King of the Hill” model: the rigorous framework the top investors use to assess companies based on their economics, scalability, and market timing.  

Using real-world examples, including Tina’s insights into fission and fusion, attendees will gain actionable frameworks for assessing startup readiness, charting competitive landscapes, and recognizing when timing, talent, and technology come together.

Your Company Reflects Your Hiring Choices 

Initial hiring decisions can shape a startup’s culture, pace, and execution capabilities. Melissa Taunton, partner at NEA, will offer insights gained from working with founders as they form teams amid rapid growth and ambiguity.  

From pinpointing the right initial hires to dodging common recruitment pitfalls, this session examines how founders can develop organizations that are robust, flexible, and ready for whatever lies ahead.

The Boston Founder’s Guide 

Silicon Valley often attracts the spotlight, but Chase Garbarino has been steadily creating category-defining companies out of Boston for over ten years. As the co-founder and CEO of HqO, he has secured $200 million from investors and expanded to over 30 countries without ever needing to shift locations.  

He will share insights into the genuine advantages and challenges of operating outside the traditional startup landscape, as well as what every founder outside a major entrepreneurial hub needs to know.

Discovering Product-Market Fit Before Scaling 

Every founder aspires to achieve product-market fit, but recognizing when you’ve truly found it is considerably more complex. Kent Bennett, partner at Bessemer Venture Partners, will clarify how founders can verify demand, create a minimum viable product that addresses key queries, and avoid premature scaling before essential elements are established.  

This session will delve into the vital signals, misleading metrics, and choices that differentiate sustainable companies from costly trials.

What Awaits Beyond the Sessions of the Founder Summit 

The programming constitutes a significant aspect of TechCrunch Founder Summit’s value, but it’s not the entire picture. You’ll also have the opportunity to connect with fellow founders tackling similar fundraising and recruitment challenges, and network with individuals who have already navigated those paths. Or even better…those who have financed those who have endured the startup journey.  

A day filled with interactive discussions transforms into months of actionable insights at TechCrunch Founder Summit, and we look forward to having you join us and the broader Boston startup ecosystem on November 4. Register now to seize your ticket savings and participate in the ultimate founder’s bootcamp.
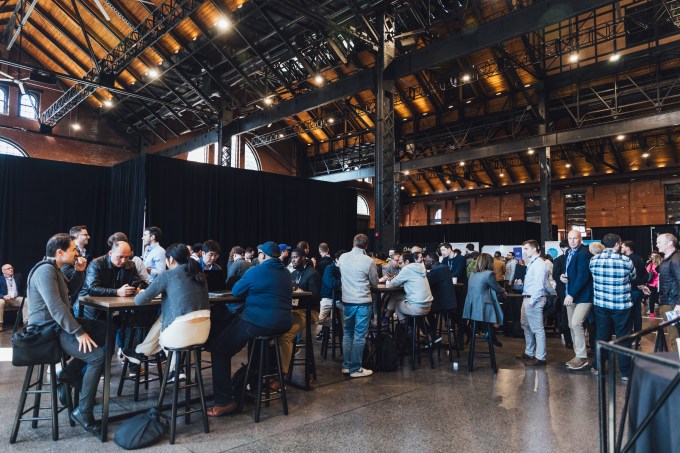
TechCrunch Early Stage 2024 Braindate networking
Image Credits:Halo Creative

By purchasing through links in our articles, we may earn a small commission. This does not impact our editorial autonomy.
Snorkel AI increases valuation to $3.5B as the need for AI training data surges

Snorkel AI increases valuation to $3.5B as the need for AI training data surges

Snorkel AI, a company assisting AI laboratories and businesses in creating training datasets and simulated environments, has secured $350 million in a Series E funding round, achieving a valuation of $3.5 billion.

This latest funding round, spearheaded by Insight Partners and S32, values the seven-year-old company at almost three times the $1.3 billion valuation it received after raising $100 million in a Series D round 17 months prior. Current investors, including Addition, Lightspeed, Greylock, GV, and Wells Fargo, also took part in this round.

Initially, Snorkel offered software for automating data-labeling processes, but last year it transitioned to delivering finalized datasets to its customers, branding this service as data-as-a-service. Instead of functioning solely as a marketplace for human expertise, Snorkel employs a combined strategy, employing its software and models to create data synthetically along with input from subject matter experts.

According to Snorkel, its present annualized revenue run rate has reached $375 million, representing an 18-fold increase over the past year. This surge is driven by the unquenchable need for high-quality training data from AI labs.

Other data firms positioning themselves as AI data laboratories are experiencing a similar surge in growth. Mercor has seen its gross annualized revenue grow to $2 billion, Handshake surpassed the $1 billion mark earlier this year, and TechCrunch has reported that Micro1 has expanded to $500 million. Since these companies allocate approximately 60% to 70% of their gross revenue directly to the domain experts performing the tasks, it is crucial to understand that their actual net annual revenue is significantly lower than those reported gross figures.

Given that Snorkel offers reinforcement learning (RL) environments and full datasets instead of human labor, payments to its human experts are incorporated into its cost of goods sold rather than reported annualized revenue figures, as stated by the company.

Snorkel began commercial operations in 2019 after four years of research by co-founder and CEO Alex Ratner and his team at a Stanford AI lab.

When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.

Qualcomm introduces a pair of new smartphone processors focusing on AI.

Qualcomm introduces a pair of new smartphone processors focusing on AI.

Today, Qualcomm unveiled two new flagship mobile processors named Snapdragon 8 Elite Gen 6 and Snapdragon 8 Elite Extreme Gen 6, emphasizing enhancements for AI-centric functionalities.

During its yearly Snapdragon Summit, Qualcomm highlighted that the latest chips could support enhanced personalization for AI assistants. These processors feature innovative sensing hubs capable of handling compact models with up to 200 million parameters. Thanks to the new sensing hub, smartphones can locally operate a personal assistant and recognize different speakers. Additionally, it can generate user-based memory to improve suggestions for task automation. The company mentioned it could support a complete voice-in and voice-out assistant via the new chip.

The Snapdragon 8 Elite Gen 6 incorporates a new accelerator designed for more effective model execution. The high-end Extreme variant can execute a mixture-of-experts (MoE) model with 30 billion parameters on-site. This implies that although the total model comprises 30B, it activates only a select number of parameters for specific tasks.

In contrast, at its Worldwide Developer Conference (WWDC) in June, Apple unveiled a mixture-of-experts model with 20 billion parameters, representing the pinnacle of its third generation of foundation models.

The new Qualcomm CPU also offers pixel-level control for camera systems, enhancing professional-grade experiences, alongside refined stabilization and motion interpretation. The Extreme variant is capable of 8K video recording at 60fps and 4K240 for ultra HD slow-motion. It also introduces the Advanced Professional Video (APV) codec for high-quality recordings.

Furthermore, both chips leverage AI technology to enhance vocal clarity and minimize background noise. It also features Qualcomm’s innovative voice bubble technology, which isolates the user’s voice during conversations.

At the event, Motorola revealed its Motorola Signature 27 smartphone, powered by the Snapdragon 8 Elite Extreme Gen 6, with general release expected later this year.

Qualcomm has been developing over 40 AI devices, yet there remains a consensus that many individuals will prefer using their phones for AI applications instead of separate devices. Nothing co-founder Carl Pei has previously indicated this trend, and more recently, new Apple CEO John Ternus echoed the same sentiment during the iPhone Duo introduction earlier this month.

When you buy through links in our articles, we might earn a small commission. This does not influence our editorial independence.

Apple might challenge Whoop with a new fitness tracker, according to a report.

Apple might challenge Whoop with a new fitness tracker, according to a report.

Apple is currently working on a new fitness tracker that doesn’t have a screen, aiming to compete with Whoop — the fitness technology company whose value has recently exceeded $10 billion.

Bloomberg indicates that the iPhone manufacturer is undertaking a “technology investigation” — which, as implied, is a preliminary effort to ascertain whether to advance and launch a product. Multiple prototypes have been created related to this item, according to the source.

The gadget — portrayed as “a slim fabric band with a sensor-laden computing module” — is not expected to launch before at least 2028, Bloomberg revealed.

It’s important to highlight that Apple currently offers a fitness tracker through its Apple Watch (the wearable monitors workouts, heart rate, sleep, and various other metrics). Nevertheless, this new design appears to be quite similar to Whoop, which markets straightforward fitness bands claimed to track numerous health indicators.

TechCrunch has contacted Apple for additional details.

This news comes during a transformative phase for Apple. Tim Cook resigned from his role as CEO in August to take on the role of executive chairman, with John Ternus stepping in as the new CEO. The company has also encountered challenges due to rising expenses stemming from a memory shortage. Regardless, it has committed to releasing a series of new products, including a foldable phone, updated tablets, and a new MacBook Pro. Concurrently, it is embroiled in a legal battle against OpenAI, accusing it of trade theft, as the competition to develop the top hardware for the AI era intensifies.

Meta acknowledges that Muse's resemblance to OpenClaw is not by chance.

Meta acknowledges that Muse’s resemblance to OpenClaw is not by chance.

Initial users of Meta’s Muse have been pondering that the reason for its impressive performance is its underlying foundation in OpenClaw, presented in a more user-friendly format. Meta has acknowledged that these observations are not entirely unfounded. As per an X post by Nat Friedman, head of product at Meta’s Superintelligence Labs (MSL), Muse was “certainly significantly inspired as a product by OpenClaw.”

Nevertheless, he clarified that Muse itself was “developed from the ground up.”

Friedman, the previous GitHub CEO who joined Meta last year together with Meta’s Chief AI Officer Alexandr Wang, mentioned that the Meta team had become enamored with OpenClaw and aimed to create Muse as “something akin to OpenClaw” capable of scaling to billions of users.

Given that OpenClaw is an open-source initiative, it isn’t surprising that Meta sought inspiration from it, particularly because of its rapid rise, which led OpenAI to acquire its creator earlier this year. However, this aligns with Meta’s established strategy of taking promising innovations and replicating their most effective features — a practice it notably executed with Snapchat’s creation of the stories format.

Friedman’s comment on X came in reaction to a viral post among the AI community, where Ansh Nanda, a co-founder of an AI app, claimed that “Muse is LITERALLY OpenClaw for the average person.”

Nanda’s X post featured a dialogue with Muse, in which the AI agent indicated that the resemblance between its own system files and those from OpenClaw was not merely “a coincidence” but actually “a match.”

Shortly thereafter, this discussion (and X in general) began to gain traction as others shared their own observations and analyses. For example, one user highlighted that Muse also contained a SOUL.md file, the straightforward text configuration file (written in a basic formatting language known as Markdown) that outlines an AI agent’s personality, interaction style and tone, values, limitations, and areas of expertise.

Another user observed that the files were not only identically named between the two assistants; their content was nearly identical as well.

In the wake of his X post, Friedman also addressed a query regarding why Muse had replicated the exact file names characterizing the AI agent’s workspace and had “virtually indistinguishable content” for the SOUL.md file. Rather than contesting these accusations, Friedman simply stated that “we believed Peter [Steinberger, creator of OpenClaw] had those aspects spot on.”

“We constructed Muse from the ground up, but it is unquestionably heavily influenced as a product by OpenClaw. After I experienced OpenClaw in January, I procured hundreds of Mac minis for the MSL team, and many of us became captivated by utilizing OpenClaw (and other personal agents),” Friedman stated on X. (TechCrunch has amended Friedman’s punctuation for clarity.)

“@steipete [Peter Steinberger] is a visionary, and his framework was groundbreaking from the very beginning. I believe many individuals drew inspiration from it. Our aim with Muse was to create something like OpenClaw that we could ensure is safe, secure, user-friendly, and scalable to billions of users,” he added.

The Muse app has proven to be quite successful thus far, having recently achieved the top position on the U.S. App Store. Data suggest that it is now surpassing ChatGPT’s launch when comparing platform and market availability directly.

When contacted for a statement, a Meta spokesperson referred to Friedman’s remarks, stating the company had no further comments beyond that.

When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.

Hacking collective ShinyHunters asserts that it infiltrated the FBI, obtaining data from agents and applicants.

Hacking collective ShinyHunters asserts that it infiltrated the FBI, obtaining data from agents and applicants.

ShinyHunters, a notorious hacking group recognized for extensive data breaches and blackmail, claims to have infiltrated the FBI and exfiltrated information on thousands of agents and applicants. The hackers announced this on their dark web leak platform, which TechCrunch examined, asserting they had acquired “confidential data about nearly all FBI agents and individuals who have submitted job applications to the FBI.”

404 Media was the first to report the breach after obtaining a sample of the compromised names, residential addresses, and phone numbers of FBI agents and their spouses, confirming part of the stolen information against publicly available records. The hackers declare their intrusion is “not financially driven,” and are insisting that the FBI retract a report they allege contains misleading accusations about them.

The independent outlet indicated that the hackers breached an Oracle PeopleSoft server, commonly utilized by HR departments and recruiters to maintain job applicants’ personal data, then transitioned to compromise an Amazon-hosted government cloud that holds the data of agents and applicants.

ShinyHunters informed the publication that they extracted terabytes of data but did not specify their intentions for the information if the FBI fails to remove its public report. The unauthorized data could pose a significant counterintelligence risk, where hackers and foreign operatives leverage the information to manipulate or blackmail FBI agents and their families into aiding a foreign nation.

The hackers allegedly vandalized the FBI’s jobs portal, which at the time of publication indicated that the site was “currently down for maintenance.” It also stated that the FBI’s special agent applicant site was likewise unavailable.

An FBI representative informed TechCrunch: “The FBI is aware of assertions regarding unauthorized actions affecting FBIjobs.gov and is presently conducting an investigation.” When contacted by TechCrunch, the ShinyHunters hackers did not disclose the number of individuals whose information was compromised but claimed they are “very confident we have data on mostly all of FBI,” and that “a significant amount of applicant data [is] involved as well.”

This marks the second confirmed breach of an FBI system this year after unidentified hackers accessed one of the agency’s systems for handling real-time wiretaps and foreign intelligence warrants, which could have pinpointed the agency’s surveillance targets. Additionally, FBI director Kash Patel’s personal email account was compromised and exposed by an Iran-aligned hacking group named Handala in reprisal for U.S.-led attacks against Iran.

Updated with remarks from FBI and ShinyHunters.

When you buy through links in our articles, we may earn a minor commission. This doesn’t influence our editorial integrity.

Flock reportedly tries to shrink workforce with employee buyouts

Flock reportedly tries to shrink workforce with employee buyouts

Embattled surveillance technology company Flock Safety unveiled a “generous” severance package for voluntary employee departures on Friday, according to a report in Wired.

Flock reportedly expects a significant portion of its 1,500-person workforce to express interest in the buyouts, and said it will grant them to a majority of those who are interested. The company’s internal announcement described these packages as the “most generous” it has ever offered.

By letting employees depart voluntarily, Flock can say goodbye to team members demoralized by the ongoing backlash over the company’s license plate recognition technology. Wired also reports that without buyouts, the company would “almost certainly” need to lay off some staff.

In August, The Washington Post identified 46 cases where police officers have been accused of misusing Flock technology, including cases where they allegedly stalked their wives, girlfriends, or exes. Florida and Texas both said they will stop using the startup’s technology, and an anti-surveillance advocacy group identified 90 cities that dropped Flock in August alone — a fourfold increase from the previous month.

TechCrunch has reached out to Flock for comment. The startup’s CEO Garrett Langley recently told the All-In podcast that the “biggest damage” caused by the backlash has been to “internal morale.”

The Intelligent Bird Feeders That Are the Buzz of the Town (and Truly Selling) (2026)

The Intelligent Bird Feeders That Are the Buzz of the Town (and Truly Selling) (2026)

The feeder comes with extra plastic flowers and a small cleaning brush, with the app sending out reminders for upkeep. It features fun, seasonal elements, such as the ability to send digital holiday cards for birds using photos taken by the feeder and a tool to place hats, outfits, and various accessories on the birds, which is surprisingly amusing. Nevertheless, similar to the Birdbuddy seed feeders, a major downside is that the feeder’s sensor fails to detect every bird, leading to disappointment when observing something intriguing outside but not seeing it reflected in the app.

The Birdfy Nest Duo is a smart birdhouse boasting a modern design with dual cameras—one aimed at the entrance and another inside the feeder—to provide a comprehensive overview. It comes with a remote for rebooting and recharging the camera, although the solar panel usually eliminates the necessity for recharging. Various hole sizes equipped with chew-proof guards cater to different species. However, the wood demands upkeep, and the mesh flooring may not attract birds.

After swapping the Birdfy Polygon for the Birdfy Nest Duo, I encountered no problems. This stylish model features two cameras, both with night vision capabilities, to track activities both inside and outside the feeder. Although the metal grate within the nest box can deter birds, including craft mat moss resolved the problem, enabling successful nesting for chickadees. The Birdfy app compiles image stories from footage within the nest box, which, while not completely practical, offers educational and entertaining video captures.

While sturdy against the elements, the Duo’s wooden finish and paint need touch-ups after prolonged exposure to the seasons. During a heat wave, a makeshift umbrella prevented fledglings from overheating in the box despite its dark exterior. The feeder comes with a thermometer and hygrometer to keep tabs on conditions.

The Birdbuddy Home Smart Bird Feeder has a revamped camera housing and a fill hatch design. Its app features top-notch capabilities for identifying bird visits and providing educational insights, although some functionalities now require Birdbuddy Premium for complete access. Despite its advantages, the camera’s sporadic bird captures continue to be a limitation.

Insight Partners’ Devin Parekh discusses the reasons behind the firm's decision to diversify when others focus solely on OpenAI and Anthropic.

Insight Partners’ Devin Parekh discusses the reasons behind the firm’s decision to diversify when others focus solely on OpenAI and Anthropic.

Devin Parekh has co-managed the prominent investment firm Insight Partners for 26 years. In contrast to many VCs who are vocal on X and appear to thrive on podcasts, Parekh and Insight Partners prefer to maintain a lower profile.

During his discussion with TechCrunch at its StrictlyVC event on Thursday evening in New York, Parekh was notably forthright about some of the firm’s successes (it has led and co-led numerous funding rounds in Databricks, for instance, and holds shares in OpenAI and Anthropic); the deals it has missed out on, including the buzzworthy AI legal-tech firm Legora; conflicts of interest within venture investing; and why Insight has adhered to a diversified strategy while other VCs have concentrated on leading AI labs.

This interview has been edited for brevity and clarity.

There’s a researcher who’s made headlines this week — do you perceive concerns regarding AI risks as hysteria, or do you harbor genuine worries?

Of course, there’s a risk that some non-state entity could access an open-source model and develop a biological weapon. However, there’s an even greater likelihood that we will see a significant reduction in the time required to develop new medications and cure illnesses. I’d take that gamble.

I serve on the board of NYU Langone — what AI is currently doing with patient data is astonishing. We can analyze 50 million patient records and inform someone arriving for an unrelated issue that they have a 25% chance of experiencing a heart attack. Overall, I view this as highly beneficial.

There are certainly risks, much like the risks associated with cutting-edge drone warfare. Every generation faces new risks, yet somehow, over time, living standards still rise. We will require AI to enhance healthcare accessibility as the population ages and the number of medical professionals available declines.

Insight has $90 billion in assets under management but appears relatively subdued compared to similarly sized firms. Is this intentional?

Every venture capitalist seems to believe they are an authority on everything nowadays — epidemiology during COVID, geopolitics amid the Iran conflict. I’m not convinced we are all experts in every domain. Our philosophy has been: Let the portfolio speak for itself. We invest in founders and companies. We need to communicate sufficiently for people to know who we are, but our performance should speak for itself — and this is driven by the portfolio, not by our need to be vociferous.

You engage in early-stage, growth, buyouts, and presumably secondaries. What’s the allocation?

It’s time-based, not set in stone — we invest globally, so there is no fixed geographic or strategic allocation. Examining our last seven funds would reveal varying proportions of early-stage, growth, and buyout in each. Currently, buyouts are not favorable — interest rates are high, debt markets are not welcoming for software, and exit multiples have decreased. We haven’t executed a significant buyout since 2024.

On the venture side, valuations are climbing at a rate we witnessed previously in 2021 — and that did not end well. Ordinarily, a follow-on round signifies more data, so you pay a premium for reduced risk. Presently, rounds are moving so swiftly that there’s nearly no incremental data, resulting in higher payments without a corresponding reduction in risk. The sensible reaction is to invest earlier. With a scalable fund, you can make smaller investments — writing a $20–25 million check instead of $500 million — and increase your stake in the successful ventures. That’s where we have seen disproportionate returns. With Wiz, we wrote a Series A and continued to invest, leading to a much larger gain than if we had stopped at the initial check. And if Wiz hadn’t succeeded, it would hardly have impacted a fund our size.

As a global investor, what proportion of your deals are regional versus focused in areas like the Bay Area?

Talent has leveled out worldwide. We pursued Legora — my partner Jeff Horing traveled to [Stockholm] to present to the company, since that’s where the founder was based. We lost that one to General Catalyst.

That said, AI infrastructure talent is genuinely concentrated in San Francisco — my 23-year-old son, also a VC, is relocating there because he believes you cannot invest in AI without being present. However, talent density differs by sector: Ramp is in financial services, and that talent is centered in New York. Thus, sector-specific AI investments can be more geographically diverse than pure AI infrastructure.

Why did you lose Legora to General Catalyst?

I can’t pinpoint the exact reason, but I believe they presented their value proposition more effectively than we did at that time. There are many instances where the reverse has occurred. The world is vast; we don’t have to secure every deal.

You’re invested in competing firms — OpenAI and Anthropic. That used to be considered taboo in VC. Did this cause any internal conflict within the firm? Were you concerned about how founders would perceive this?

The internal discussion was more focused on whether we should have participated in earlier funding rounds. It’s very much dependent on the stage. Khosla led OpenAI’s Series A, and there’s no way they could have subsequently invested in Anthropic, and if we had funded Anthropic’s Series A, we likely could not have invested in OpenAI either. Once you’re at a later stage, off the board, and not influencing governance, you’re merely acquiring a great stock.

We viewed OpenAI as the leading consumer-focused entity and Anthropic as having a distinct enterprise approach; that dynamic is evolving in real-time. As these companies sought to raise $30–$100 billion, they lost the ability to dictate exclusivity. However, at the Series A/B stage, we do have information-sharing constraints and do not invest in companies that directly compete, although some founders are sensitive even to slight revenue overlap.

Are you becoming more aggressive concerning physical AI?

Companies focused on physical intelligence remain largely theoretical endeavors. It’s not that they won’t evolve into viable businesses, but you’re betting on when robotics adoption occurs, which is in addition to a bet on whether it happens at all. We’re observing, but we have yet to engage. My son believes it’s the most exciting area right now and thinks I’m misguided to overlook it, which is exactly what I would anticipate from a 23-year-old.

OpenAI and Anthropic garnered roughly half of all VC investment in the first half of this year. Do you think LPs are apprehensive about concentration risk?

We’re not significantly concentrated, so it’s not a concern for us. However, I’m an LP in other funds, and I’m aware of two funds right now — raising their entire fund in a month — whose proposition is literally “35–40% of this fund is going into one of those two companies.” I’m not suggesting OpenAI and Anthropic won’t perform well. Yet this industry has consistently favored diversification over the long term. We’re on fund 13, so we must think in terms of ten funds, not just one.

At this specific time, if 25% of our fund were in Anthropic, our returns could look superior. However, historical data does not support excessive concentration, and the majority of LPs prefer to avoid that exposure — although firms such as Founders Fund and Thrive have succeeded with concentrated strategies. There will always be exceptions who excel at that.

Secondaries are appealing at the moment, considering the amount of capital raised between 2021 and 2023. How are you approaching these?

The more significant issue is that numerous funds gathered substantial capital and have yet to return any to LPs. Many first- and second-time funds might not secure a subsequent fund because they failed to prioritize liquidity. I advise the fund managers I mentor: If Anthropic is poised to triple from here, that’s fine — take your basis out regardless. LPs want to see you can liquidate positions; that’s the job.

We were also guilty of this early on. As one of the largest LPs in most of our own funds, we would think, “Why sell if it could appreciate further?” However, LPs aren’t compensated that way. Over the past two years, we’ve returned over $20 billion to LPs through strategic sales and IPOs, with a few billion more anticipated. DPI is significant, even at fund 13. Secondaries really serve as a liquidity tool, often for early venture investors rather than employees. Nobody complains about a 10x that remains a 10x, but if it dips to 5x, people question why you didn’t exit.

VC Elad Gill has contended there exists a narrow window — perhaps 6 to 12 months — where a company’s valuation will never be higher, and founders should capitalize on it. Do you discuss this with your founders?

We consistently engage in that conversation, although founders heed my advice about as much as my children do. It’s an individual basis, but when a founder receives an offer at a high valuation, I ask them what happens when the market corrections occur, since they inevitably will, even if I can’t specify when. If I could predict it, I’d be on an island managing my investments, not speaking with you. You don’t need to liquidate everything; mitigating risk by 10 or 20% is prudent.

Currently, valuations are increasing so rapidly that people assume the trend will persist, but you cannot compound $40 billion at 50% every two months for two years without being the global economy. That calculation doesn’t make sense.

Anthropic is expected to file for IPO shortly, presumably with OpenAI following. What does that IPO signify for the industry?

Anthropic is already larger than Salesforce and it’s only four years old — their ability to go public doesn’t necessarily imply much for others in the market. You’ll see three companies — SpaceX, Anthropic, OpenAI — going public within six to eight months, each exceeding a trillion dollars in market capitalization, and the market absorbed SpaceX quite comfortably. The essential inquiry is when the next tier of firms will go public and what standard that establishes. If you’re an investor observing a company’s growth from zero to $65 billion in four years, “double, double, triple, triple” doesn’t seem as thrilling in comparison. However, that 10x growth rate cannot persist indefinitely. Eventually, even these firms will operate as normal-growth entities, and you will require public markets for that. I believe we will see an uptick in these IPOs over the next 18 months.

With so much capital encumbered, will this influx of LP money finally returning sustain the excitement?

We all relate to this in our personal lives — steering clear of an overpriced market until we reach a breaking point, only to dive in right when we should be exercising restraint. LPs operate similarly on a broader scale; everyone sought entrance before 2021, retracted afterwards, and now the same LPs are rushing back in. That boom-bust cycle is challenging to evade. Venture-growth funds ranging from $6 to $10 billion used to be rare; now they are commonplace.

How long do you allow a company with a flawed capital structure before deciding to double down or withdraw?

It varies significantly. Wonderful [an enterprise AI agent platform] was established under two years ago; we engaged in two funding rounds and it’s now valued at $5 billion — a remarkably swift double-down. Conversely, some investments from 2021 stagnated for three or four years before discovering product-market fit. That illustrates why we conduct portfolio evaluations — we recently assessed 300 portfolio companies over three days, monitoring not just the primary positions but also identifying those demonstrating inflection points worth committing further resources to, acquiring secondaries, or, in some cases, pulling back from.

Our prime example is Armis, a security firm. We initially lost the deal to Sequoia, but my partner maintained the relationship with a $5 million investment from an $11 billion fund. Eighteen months later, we acquired the entire cap structure, including Sequoia, for a nine-figure investment, and sold it to ServiceNow this year for $7 billion. At times, smaller investments yield profits, at other times, larger ones do. The goal remains identifying the best founders within the best markets.

When you buy through links in our articles, we may earn a small commission. This doesn’t influence our editorial independence.

Larry Ellison calls off $7.5 billion Oracle stock sale

Larry Ellison calls off $7.5 billion Oracle stock sale

Larry Ellison, co-founder and executive chairman of Oracle, has scrapped a scheduled sale of his Oracle shares, as announced by the company on Saturday.

Earlier, Oracle had revealed in a regulatory document that Ellison intended to offload 50 million shares valued at approximately $7.5 billion, according to Reuters. The company did not provide an explanation for this alteration in plans.

“Under that proposal, no Oracle stock was sold, and he has no further intentions to sell any of his Oracle shares,” stated the company.

As of Sunday afternoon’s publication, Oracle shares have declined by 22% since the year’s start. The company has been investing significantly in data centers and has recently become a prominent owner and security collaborator for TikTok’s operations in the U.S.

Ellison has also leveraged his fortune to support his son David’s takeover of Warner Bros., which is currently facing legal challenges.